The trouble with calling speculative bubbles a feature of capitalism is that everyone remembers the survivors. Nobody remembers how bad the last war really was.
I’m a fan of Ed Dowd and read him pretty regularly. He makes an interesting argument in his recent Substack essay, “Investment Bubbles Are a Feature of Capitalism, Not a Bug“. His proposition is familiar: speculative booms finance infrastructure that survives the inevitable financial collapse. Railroads, electrical grids, and dot-bomb era fiber-optic networks were all overbuilt during speculative manias. Investors lost fortunes, companies went bankrupt, but society eventually benefited from the infrastructure left behind.
There is considerable historical truth to this argument. Unfortunately, I think it substantially understates the problem with the artificial intelligence bubble. Not because Dowd is wrong about speculative finance, but because this time the consequences may extend far beyond the investors who made the bets.
I say that as a veteran of the dot-bomb collapse. I was there for the last war. And one thing I’ve learned is that, with the passage of time, everyone remembers the victories, the heroic survivors, and the technological progress. Very few remember how bad the war actually was. And who went to prison or should have.
It’s easy to look back at the dot-com bubble and see Amazon, Google, and the great expansion of the Internet (not to mention Salesforce, PayPal and Nvidia itself). It’s harder to remember the rabid fear of missing out, the many, many businesses that disappeared, the employees laid off, the careers interrupted, the savings wiped out, the layoffs, the bankruptcies, and the communities that experienced the collapse as something considerably less abstract than creative destruction.
The historical narrative makes the winners inevitable and the losers incidental. They weren’t incidental at the time and the only thing that seemed inevitable was the financial wipeout.
The Survivors Write the History
The comforting story about the dot-com crash is that companies built too much fiber-optic infrastructure, the telecommunications companies went broke, Socks.com was a joke, and the next generation acquired the assets at bargain prices. Everyone eventually got cheaper bandwidth, and the Internet flourished. There is truth in that story, too. But it compresses years of financial destruction into a happy ending. The market may sort itself out in the long run, but it’s also true that in the long run we’re all dead.
The NASDAQ Composite fell approximately 78% from its March 2000 peak to its October 2002 trough. Companies evaporated. Investment capital disappeared. Workers who had been told they were participating in an inevitable technological revolution discovered that inevitability did not extend to their employment or stock options. Some investors could afford to wait for the next cycle. Others could not.
Dowd doesn’t deny that destruction. In fact, he describes it. What I question is his conclusion that the surviving infrastructure demonstrates that the process was ultimately a net positive. That conclusion requires accounting for the losses as well as the gains.
The important question is not whether the Internet ultimately succeeded which I guess it did if you weren’t in the music business. The question is whether that eventual success justified every speculative investment made in its name, or excused the damage caused along the way.
I suggest that it did not. And that brings us to AI. Let’s leave aside the sector-specific existential harm. The internet came for the music business—AI is coming for musicians. But there’s a lot more to worry about this time.
This Time We’re Not Just Rolling Up Dark Fiber
Dowd’s historical analogy becomes much less reassuring when we look at the physical characteristics of the assets being created. Fiber-optic cable is relatively durable infrastructure that powers the Internet. Railroad rights-of-way can have value for generations. Electric transmission systems can support a wide variety of economic activities. But artificial intelligence data centers are something else.
Data centers depend on extraordinarily expensive computing equipment that depreciates rapidly and may become economically obsolete long before the buildings housing it deteriorate. Their cooling systems, electrical configurations, and operating requirements can be highly specialized. Their profitability depends not merely on the existence of demand for computing, but on whether that demand will support the continuing expense of providing it.
Buying a bankrupt railroad at twenty cents on the dollar is one proposition. Railroad tracks can be upgraded. Buying a bankrupt AI data center filled with yesterday’s chips, whose replacement costs may exceed the market value of the enterprise, is quite another. Some of the associated infrastructure will certainly retain value. Transmission lines, substations, and buildings may find alternative uses. But we cannot simply assume that every billion dollars invested in AI infrastructure becomes a permanent billion-dollar contribution to society.
The distinction is between infrastructure that becomes cheaper after a financial collapse and infrastructure that becomes obsolete. Those are not the same thing. I don’t see a conga line of buyers for obsolete chips.
Railroads Didn’t Destroy Aquifers
There is another problem with Dowd’s historical analogy that deserves special attention. Railroads, electrical grids, and fiber-optic networks certainly imposed environmental costs. Railroads transformed landscapes, disrupted ecosystems, and facilitated resource extraction. Electric generation produced enormous pollution. These were hardly environmentally benign enterprises.
But the infrastructure itself did not ordinarily depend on consuming vast quantities of local groundwater to remain operational. Neither did they build a private electrical generator system or behind-the-meter nuclear power. A bankrupt railroad could leave behind tracks that another operator might use. A bankrupt telecommunications company could leave behind fiber-optic cable that continued carrying traffic for years.
An AI data center, especially in a water-stressed region, presents a different proposition altogether. Its operation may depend on substantial, continuing water consumption, whether directly through cooling or indirectly through electricity generation. If that demand contributes to depletion of an aquifer, the environmental loss may persist long after the data center itself becomes obsolete and the investors have evaporated.
In many rural regions, groundwater depletion can contribute to land subsidence, soil degradation, and cascading and broader ecological damage. Where combined with drought, vegetation loss, and unsustainable land use, it may also contribute to desertification.
Not every data center consumes enormous amounts of local groundwater. Cooling technology, water sourcing, climate, and local hydrology matter. But the possibility of irreversible damage ought to be accounted for before construction, not merely acknowledged after the financing collapses. God told Noah to build the Ark before the rain.
You cannot buy a depleted aquifer out of bankruptcy at twenty cents on the dollar and assume the water will return.
And that is the fundamental accounting error in the economically rational story about infrastructure bubbles. Dowd counts the value of the railroad tracks, the generating stations, and the fiber-optic cables that survived the speculative crash. We also need to account for the natural resources consumed, the landscapes transformed, and the public liabilities left behind? The prospect of further public support if private capital retreats is not hypothetical policy territory; it is a risk worth examining before commitments become irreversible.
The comparison becomes even more troubling when the useful life of the computing equipment may be measured in years while the consequences of groundwater depletion may persist for generations. The railroad tracks survived the railroad bubble. Will the aquifers survive the AI bubble? That is a considerably more serious question than whether investors will eventually find bargains among the wreckage.
The Land, the Water, and the Electricity Don’t Go Bankrupt
The aquifer problem illustrates a larger weakness in Dowd’s analysis. Financial capital is not the only resource being consumed. Across the country, communities are being asked to accommodate immense data-center campuses, new generating capacity, transmission corridors, substations, water infrastructure, and associated industrial development. And indirectly, for now, bear the cost of these negative externalities.
Some projects require extraordinary amounts of electricity. Others threaten to transform agricultural land, rural landscapes, and communities whose residents never imagined they would become industrial centers serving the AI economy. Much less find their family homes taken by eminent domain to build power plants, transmission lines, and substations.
The AI investors can measure their exposure in dollars and securities. The communities may measure theirs in acres, gallons, utility bills, and lost opportunities to use their land and resources for other purposes. These are different kinds of risk.
If an AI developer goes bankrupt, the investors may write down the value of the enterprise. The local aquifer does not receive a corresponding write-up. The farmland does not automatically return to agricultural production or the original family owners. The transmission corridor does not disappear. And the surrounding community does not recover the years spent fighting over its future.
Financial losses can be discharged or restructured in bankruptcy. Environmental damage and community disruption often cannot. The problem with using the history of infrastructure bubbles to rationalize today’s AI buildout is that it assumes the surviving infrastructure represents a residual benefit without fully examining what was consumed to create it.
A financial bubble can destroy financial capital. An infrastructure bubble can also destroy natural capital. One is fungible and can be replaced. One is not fungible and cannot be replaced. And unlike a distressed asset, depleted natural capital may not be available for purchase, refinancing, or reuse. Nature may not give us a second act.
The Bailout Has Already Begun
There is another feature of the AI bubble that makes the comparison to earlier infrastructure booms particularly questionable. The public is already helping finance it whether they realize it or not.
Across the country, state and local governments are granting data-center developers sales-tax exemptions, property-tax abatements, infrastructure incentives, and other subsidies. According to the National Conference of State Legislatures, 38 states offer dedicated data-center tax incentives. Many beneficiaries are among the wealthiest and best-capitalized corporations in history. These are not struggling entrepreneurs who cannot obtain financing for a promising new invention. They are companies spending extraordinary sums on infrastructure they insist is indispensable to their future profitability. And their biggest allies include the President of the United States and the World Economic Forum. These are not plucky little startups.
If the investments are so compelling, why must taxpayers subsidize them?
The answer is not self-evident. Yet the public is already surrendering tax revenue to support a speculative investment cycle whose ultimate economics remain uncertain. Call these incentives economic development if you like. From the taxpayer’s perspective, they are a subsidy today, not a hypothetical bailout tomorrow.
And that brings us to the increasingly circular character of AI financing.
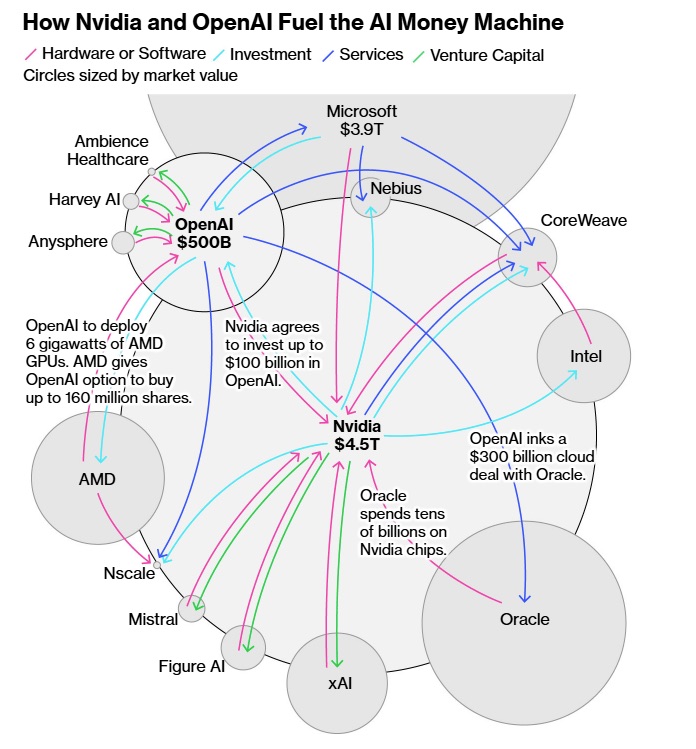
Major technology companies invest in AI developers that purchase their computing services. Chipmakers like Nvidia provide financing and guarantees for projects that buy their chips. Cloud providers commit capital to customers that commit to buying cloud capacity. Nvidia’s own securities filings disclose substantial guarantees supporting AI infrastructure leases, illustrating how suppliers, customers, and financiers can become financially interdependent. Each transaction may have a legitimate commercial explanation. Collectively, however, they raise an uncomfortable question: How much of the AI industry’s apparent demand is being financed by the same companies that benefit from supplying it? Where is the ROI?
The distinction matters because customer financing is not the same thing as independent customer demand. A company can sustain enormous spending commitments while investors remain willing to supply fresh capital. But eventually the enterprise must generate enough revenue from customers outside the financing circle to justify the investment.
What happens when the new money slows down? Not that it’s a ponzi scheme or anything.
The developers may still owe billions under computing contracts. The lenders may still hold debt secured by rapidly depreciating equipment. The utilities may already have built transmission and generating infrastructure. And the communities may already have surrendered tax revenue, groundwater, farmland, and control over their surroundings.
At that point, the “Because China” argument for further public assistance practically writes itself: these facilities are essential to national competitiveness, the electrical infrastructure has already been built, the jobs must be protected, and allowing the industry to collapse would threaten the broader economy.
That pressure from Washington DC does not conclusively establish that another TARP-style bailout is inevitable. It establishes that the circumstances in which one might be demanded are foreseeable and are already on the horizon.
The taxpayer is already subsidizing the boom. The danger is that the taxpayer will also be asked to finance the bust. And unlike the venture capitalists, the taxpayers never agreed to make the investment. And most of them wouldn’t want more AI if anyone asked.
Who Gets the Bill?
Those existing subsidies are only the first layer of public exposure. The second is the risk that utilities and governments will be left supporting infrastructure built for demand that never fully materializes. The AI buildout increasingly depends on institutions that extend well beyond the private investors making speculative bets.
Consider an electric utility that expands its transmission and generation resources to accommodate anticipated data-center demand. If the demand materializes and the customer pays its full share, the investment may be justified. But what happens if the developer disappears, the project is canceled, the promised electrical load never materializes, or technological improvements make the facility uneconomic?
Who pays for the infrastructure? The answer depends on utility contracts, regulatory treatment, and financial guarantees. But absent adequate protections, some costs may be shifted to ordinary ratepayers. People who never invested a dime in artificial intelligence may find themselves paying for an unsuccessful artificial intelligence investment through their monthly electric bills or a taxpayer bailout.
That is not creative destruction. That is the socialization of private speculative risk. Similar questions arise with tax abatements, public infrastructure improvements, water-system expansions, and other incentives offered to attract developments promising extraordinary economic benefits. And there is a particularly troubling possibility: communities may end up paying for infrastructure that no longer has the economic purpose used to justify its construction.
A railroad might be reorganized and continue carrying freight. A transmission line built primarily to serve an anticipated AI load could become an expensive stranded asset if the demand never arrives. The investors may be gone. The ratepayers will still be there. I give you Amtrak.
The New Gold Rush Is Taking Place in Someone Else’s Backyard
One striking characteristic of the data-center expansion is the increasingly organized resistance from ordinary people. In Texas, Georgia, Virginia, and elsewhere, communities are confronting proposals that could permanently change the character of the places where they live. Their objections are not necessarily objections to technological progress. They are often objections to who gets to make the decisions, who receives the benefits, and who bears the costs.
A developer can describe a 900-megawatt data center as an investment in the future. The people living nearby may see an enormous industrial load competing for electricity and water, accompanied by transmission lines, altered landscapes, uncertain employment benefits, and possible increases in their utility bills. Both descriptions may refer to the same project. But only one necessarily appears in the investor presentation.
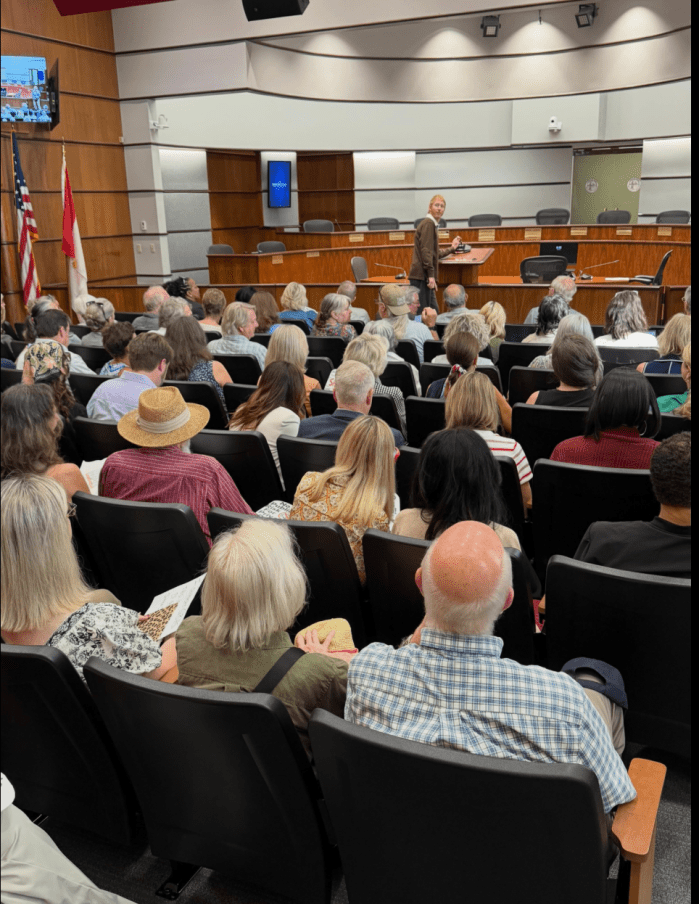
There is a fundamental difference between financing speculative infrastructure with voluntary investment capital and requiring a community to absorb the environmental and economic consequences of that speculation. The residents are not venture capitalists. They did not buy shares in an AI company. They were not promised equity in exchange for the use of their groundwater, their electrical infrastructure, or their community’s future.
And they should not be treated as involuntary guarantors of the industry’s business model.
The Economics of Obsolescence
Dowd correctly identifies the threat that lower-cost AI models, increasing competition, and changes in the economics of computing pose to current investment assumptions. But this observation also undermines the conclusion he draws from the historical infrastructure cycle. As AI models become dramatically more efficient, today’s infrastructure may well prove unnecessary or uneconomic very quickly.
Certainly, cheaper computing could stimulate additional demand. That possibility should not be dismissed. But neither should the opposite possibility: technological progress may undermine the value of facilities whose investors assumed that computing requirements would continue growing along a particular trajectory.
A railroad track laid in 1873 might remain useful in 1923. A data center designed around a particular generation of GPUs may become economically obsolete in a fraction of that time. But the data center industry tells communities that these projects are long-term investments. The industry’s own research anticipates major infrastructure renovations within the first decade and continual replacement of computing equipment. The question is not simply whether a data center becomes obsolete. It is who pays to keep it from becoming obsolete—and who bears the “stranded asset” costs if the economics stop working.
Research from Microsoft published in 2026 acknowledges that successive generations of AI hardware demand greater electrical power and more demanding cooling systems, potentially making existing data center infrastructure obsolete. Modern high-density GPU racks can produce four to eight times the heat of conventional CPU systems. (Rearchitecting the Datacenter Lifecycle for AI: A TCO-Driven Framework (https://arxiv.org/abs/2509.26534), Jovan Stojkovic, Chaojie Zhang, Íñigo Goiri, and Ricardo Bianchini, Microsoft Research, ISCA 2026, June 2026.). This is not merely a matter of replacing servers. It can require substantial reconstruction of electrical distribution, cooling systems, and physical facilities.
Industry reporting (https://www.datacenterknowledge.com/data-center-construction/ai-demands-stretch-the-limits-of-data-center-retrofits) confirms that existing data centers are already encountering these limits. Facilities designed for conventional computing may be unable to accommodate the power density, liquid cooling, and structural loads of newer AI systems without extensive renovation. Some can be economically retrofitted. Others may be unsuitable for the next generation of hardware.
And what happens when an operating data center finally closes? An August 2026 analysis from Columbia Law School’s Sabin Center for Climate Change Law warns that abandoned hyperscale facilities may be exceptionally difficult to repurpose.(https://blogs.law.columbia.edu/climatechange/2026/08/06/decommissioning-data-centers-avoiding-stranded-assets/) Their enormous size, specialized infrastructure, electrical equipment, and environmental cleanup requirements distinguish them from ordinary commercial buildings. The analysis recommends mandatory decommissioning plans and financial assurance mechanisms, including bonds, to prevent communities from inheriting the cleanup bill. Some Pennsylvania jurisdictions have already adopted such requirements, including provisions for decommissioning and financial security.
There is no reliable national count of data centers already rendered economically obsolete by AI. That absence of data should not be confused with an absence of risk. The evidence instead reveals an industry facing rapid technological change, recurring capital requirements, uncertain future demand, and substantial public infrastructure exposure. Before granting tax abatements, expanding transmission capacity, or committing scarce water resources, communities should demand answers to four questions: How long will this particular facility remain economically competitive? Who pays for its upgrades? Who pays if the developer leaves? And who guarantees that the land and infrastructure will be restored if the project fails?
A server can be replaced. An aquifer cannot necessarily be restored. And a community should not be expected to underwrite the consequences of technological obsolescence while the developer keeps the upside. More importantly, the environmental consequences of building and operating that facility may substantially outlast the useful life of its equipment. This is the uncomfortable asymmetry at the center of the AI investment bubble.
The technology may become obsolete quickly. The environmental consequences may not. There is no reason to assume that the next generation of AI companies will need precisely the gigantic facilities being built today, or that the residual value of those facilities will justify the resources consumed and liabilities incurred in their construction. That would be the first time that evolving technologies got bigger rather than smaller. The fact that some entrepreneurs may eventually purchase distressed AI infrastructure at bargain prices does not establish that society received such a bargain.
The Cost to Human Creativity
Unlike the earlier infrastructure booms, generative AI is being promoted not simply as a means of increasing human productivity but also as a substitute for human work. In the music business, the distinction is especially apparent. Companies developing generative AI systems have used enormous quantities of copyrighted works in circumstances that have generated substantial disputes over authorization, compensation, and the rights of the people whose creative labor supplied the underlying material.
The industry’s investment proposition squarely depends on capturing the value of human creativity while reducing the cost of obtaining it. That introduces another kind of potentially irreversible consequence. An artist whose livelihood is displaced by a speculative technology cannot necessarily recover the lost opportunities when the company deploying it goes bankrupt. A songwriter whose works have been used without authorization does not automatically receive compensation because an AI developer’s assets are purchased by another company. And a creative profession weakened by years of uncompensated technological substitution may not spontaneously regenerate after the market corrects.
The infrastructure bubble may leave behind computing facilities. But what happens to the human infrastructure—the trained musicians, writers, performers, and other creators whose work helped make the technology possible? That question is missing from the traditional story about technological progress emerging from financial wreckage.
Everyone Forgets How Bad the Last War Really Was
Perhaps the most troubling feature of Dowd’s argument is not his economic historical premise, but the reassurance that some may draw from it. Yes, capitalism has repeatedly financed useful infrastructure through speculative excess. Yes, investors have repeatedly lost enormous amounts of money. And yes, subsequent generations have sometimes benefited from the wreckage.
But history is not an accounting exercise in which eventual benefits automatically erase earlier losses. As they say, in the long run we are all dead. The dot-com collapse was not an amusing intermission between the invention of the Internet and the arrival of AI. It was a devastating economic event for many people who had invested their money, careers, and confidence in what they were told was the future. You know, because China. I remember.
And unlike the dot-com boom, the AI infrastructure boom is reaching deeply into the physical environment, the electric grid, water resources, local government finances, and the livelihoods of people who never volunteered to participate. When the speculative capital disappears, those obligations and consequences may remain. That makes the stakes considerably higher than an investor’s return on capital. I’m going out on a limb here, but my bet is that the Sam Altman’s of this world could care less who loses money or has their lives destroyed. He clearly could care less about musicians and authors, I have no doubt about that part.
Dowd may be right that speculative bubbles are a recurring feature of capitalism. But that observation should lead us to a very different conclusion. If bubbles are a predictable feature of capitalism, then protecting the public from their predictable consequences ought to be an equally predictable feature of public policy. Which it most definitely is not. We should not wait for the crash to discover whether adequate safeguards were in place.
We should insist now on enforceable protections against stranded asset utility costs, meaningful financial assurances, responsible water use, environmental restoration obligations, and independent scrutiny of the economic claims used to justify these enormous projects. And we should stop assuming that the eventual survival of a technology necessarily vindicates the financial and political decisions made in its name.
The next generation may inherit valuable infrastructure from today’s artificial intelligence boom. It may also inherit obsolete equipment, depleted aquifers, stranded electrical assets, disrupted labor markets, and communities left to repair damage that never appeared on the investors’ balance sheets. Both outcomes are possible. Both belong in the analysis.
Those of us who lived through the dot-bomb years know that the history of a speculative boom looks very different from the other side of the crash. Everyone remembers who won the last war. Too few remember what the war cost.
The railroad tracks survived the railroad bubble. Will the aquifers survive the AI bubble? Will the musicians?

